America began 2032 much as it had begun most years.
The holidays were over. Children were back in school. Offices that had been half empty during the final two weeks of December were full again. Gyms were crowded with people fulfilling New Year’s resolutions, at least temporarily. Credit-card statements arrived carrying reminders of Christmas presents, travel, dinners and purchases that had seemed perfectly reasonable a few weeks earlier.
Most people were thinking about ordinary things: work, money, children, parents, health, retirement, what they wanted to accomplish during the coming year, and what they hoped wouldn’t go wrong.
Some families were struggling. Others were doing well. Many were somewhere in between, financially secure enough not to worry about every bill but not secure enough to stop thinking about money altogether.
And then there were people for whom money worked very differently.
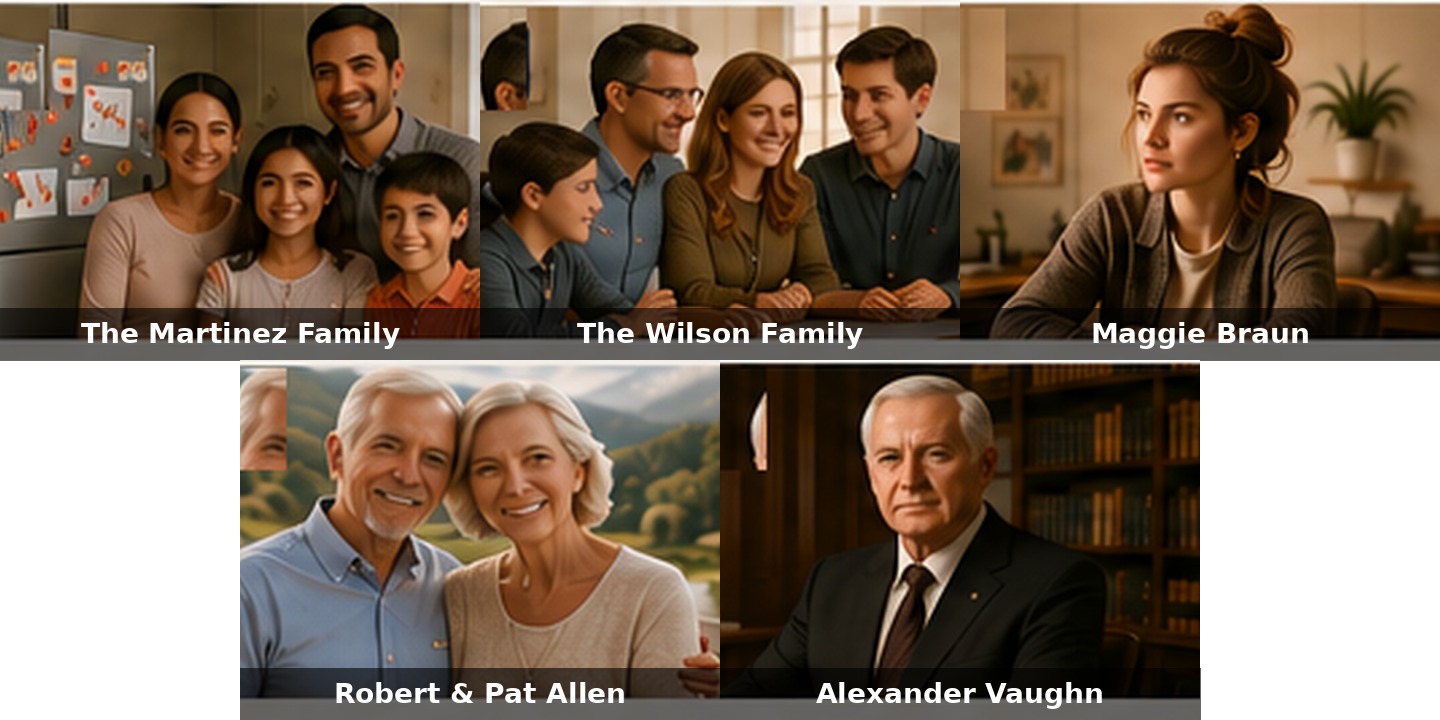
This is the story of five households.
They don’t know one another. They don’t live in the same neighborhoods. They don’t have the same friends. They don’t shop in the same places, take the same vacations or worry about the same things. There is no obvious reason their lives should ever intersect.
But before their paths cross, we need to meet them where they are.
Carlos Martinez is 39 years old. His wife, Elena, is 37. They have been married for fourteen years and have two children, twelve-year-old Sofia and nine-year-old Mateo.
Carlos works for a regional distribution company. He started eleven years ago loading trucks, a job he expected to keep only until he found something better. Instead, he discovered that he was good at it. He understood how the warehouse worked, noticed problems before they became expensive, and had an unusual ability to calm down angry people without making them feel as though they had lost an argument.
He moved from the loading dock to inventory, then to team leader, and eventually became an assistant manager.
Carlos never thought of himself as ambitious. He didn’t read books about leadership or spend much time planning his career. He went to work every day, did his job well and gradually became the person other people called when something went wrong.
Elena works part-time in the billing department of a medical office. Before Sofia was born, she worked full-time. She had always expected to return to full-time work after the children were a little older, but family schedules had a way of becoming more complicated rather than less.
Sofia had school activities. Mateo played soccer. There were dentist appointments, sick days, teacher conferences and the thousand small obligations that rarely appeared on a calendar until someone had to deal with them.
Together, Carlos and Elena earn about $65,000 a year.
They rent a three-bedroom townhouse they have lived in for six years. The neighborhood is safe, the schools are decent and the children have friends nearby.
Carlos would like to buy a house. Elena would too. They have talked about it many times.
Every year or so they look at listings online. They discuss how much they might need for a down payment. Carlos occasionally drives past a house with a FOR SALE sign and slows down enough to annoy whoever is behind him.
Then something happens.
A car repair. Dental work. A medical bill. A broken appliance. An unexpected school expense.
Nothing catastrophic. Just life.
They have a few thousand dollars in savings. Carlos has some money in his retirement account through work. Elena has a smaller account from the years when she worked full-time.
They are not poor. They pay their bills. Their children have what they need and quite a few things they don’t. They order pizza most Fridays, take a modest vacation during the summer when they can, and occasionally spend more than they planned on birthdays and Christmas.
Money does not dominate their lives. But it is almost always somewhere nearby.
James Wilson is 63. Karen is 61. James is a mechanical engineer for a large manufacturing company. Karen is a healthcare administrator.
Their daughter, Emily, is sixteen and beginning to think seriously about college. Their son, Tyler, is twenty-two. He lives at home, has never held a real job, spends more time online than either parent thinks is healthy, and has shown little urgency about deciding what comes next.
James and Karen earn approximately $275,000 a year.
When James was twenty-five, he had a very specific idea of what $100,000 a year meant. It meant rich. Not billionaire rich. Not mansion-and-yacht rich. But comfortable enough that money would become simpler.
He imagined a nice house, reliable cars, vacations, college for the children and enough savings that an unexpected bill would be inconvenient rather than alarming.
By most reasonable measures, that is exactly the life he and Karen have built.
They own a four-bedroom home in a good school district. They drive two late-model cars. Their credit cards are paid in full every month. Both contribute to retirement accounts. They have money saved for college. They usually take one good family vacation each year.
They are doing well. James knows that. Karen reminds him when he forgets.
The problem is that the life James imagined at twenty-five did not include all of the expenses that came with it: the mortgage, insurance, groceries for two teenagers, sports, cars, home repairs, college, retirement, and the roof that a contractor recently told them might need to be replaced within three or four years.
Individually, none of those expenses seemed unreasonable. Together, they had a remarkable ability to consume money.
James responds by planning. He has spreadsheets. Lots of them.
There is one for retirement. One for college. One for the mortgage. One comparing whether Karen should keep her SUV for another three years or trade it in sooner. Karen has never opened that spreadsheet.
She does not share James’s belief that every important decision improves when placed into cells with formulas.
Karen’s approach to money is different. She saves. She is responsible. But she also believes that occasionally spending money on something memorable is not a failure of financial planning.
This difference has produced many conversations and very few serious arguments.
They are comfortable. They are fortunate. And yet James has recently begun wondering why a household earning $175,000 a year sometimes feels as though it is running just fast enough to remain in the same place.
Maggie Braun is twenty-eight, single, idealistic and, in ways she does not yet recognize, a little naïve. She is four years into a career she chose because she wanted her work to matter. She is a social worker, spending her days helping families navigate housing problems, addiction, unemployment, mental-health crises and the paperwork that seems to accompany nearly every difficult moment in life.
She earns about $55,000 a year. She also carries roughly $110,000 in student debt from the undergraduate and graduate education that helped qualify her for the profession.
Maggie does not regret becoming a social worker. Most days, she believes she is exactly where she belongs. But she has begun to understand that doing meaningful work and building a secure financial life are not always the same thing.
Her rent keeps rising. Her car is aging. Home ownership feels distant. Her mother occasionally suggests she move home for a year to attack the student loans. Maggie occasionally considers it for almost eight seconds.
She believes government can do good things because she sees some of those things work. She also sees programs fail, rules collide and people disappear into bureaucracies that were supposedly designed to help them. She still tends to believe that good intentions, enough effort and the right policy can solve most problems. Experience has begun testing that belief, but it has not broken it yet.
Robert Allen is 69. His wife, Pat, is 68. They have spent most of their adult lives doing what they thought they were supposed to do: working, raising a family, paying off their home and saving for retirement.
Robert spent most of his career in corporate sales and management. Pat worked for many years as a registered nurse before moving into hospital administration.
Ten years ago, Pat was treated for breast cancer and went into remission. Three years ago, the cancer returned.
She was treated again, and today the cancer is under control. But the recurrence changed more than their health. Unexpected medical expenses ate into some of the savings they had expected to carry into retirement, and the experience made both of them less certain about how much money would be enough.
Robert had planned to retire at sixty-seven. Pat at sixty-six.
Neither did.
Now, with retirement already postponed, they have begun following the Social Security debate much more closely than they ever expected to.
Alexander Vaughn is 68.
Thirty-five years earlier, he founded Vaughn Systems, a technology company that grew from a handful of employees in rented office space into one of the largest companies in its industry.
He eventually took it public. He remained its chief executive for years, stepped down, and still owns a very large amount of the company.
Depending on what the stock market is doing, Alexander’s net worth moves around considerably. A reasonable estimate at the beginning of 2032 is about $5 billion.
Alexander has been married twice. And divorced twice.
He has three adult children.
Rebecca, his oldest, works with the family’s investments and is the child most likely to challenge him directly.
Daniel is a physician in Boston. He loves his father but has made a deliberate effort to build a life that is not organized around the Vaughn family fortune.
Michael, the youngest, is thirty-one. He has tried several businesses and careers and has not yet found anything that feels permanent.
Alexander worries about him. He would never describe it that way.
Alexander has multiple homes, a private aircraft, a staff and enough money that ordinary household budgeting stopped being meaningful a long time ago.
He can spend more on dinner than Carlos Martinez spends on groceries in a month without noticing the charge. He can gain or lose tens of millions of dollars in a single day without buying or selling anything.
Yet Alexander has never completely stopped thinking like the young man who once wondered whether his company would survive another month.
In his home office sits an old wooden desk.
It is scratched, badly matched to the room and missing a handle on one drawer. His interior designer has tried several times to replace it.
Alexander refuses.
Five households. Five very different lives. Five very different ideas about what America owes them—and what they owe America.
Let’s see how they react to the events unfolding in America 2032.
A Note to Readers
America 2032 is a work of fiction. Its principal characters and events are fictional. References to real institutions, government agencies, places and historical events are included to provide a realistic setting and do not imply participation in or endorsement of this story. Any resemblance of fictional characters to actual persons, living or dead, is coincidental.